A bankruptcy record is not a mortgage lead by itself. It is a timing signal. The difference matters because the answer to when do mortgage prospects qualify depends on the loan program, the borrower’s credit recovery, the bankruptcy outcome, and whether a lender has a product built for that file.
For mortgage marketers, the bigger question is not whether every recent filer can close this month. They cannot. The question is whether the prospect has entered the recovery window where credit, income, savings, and purchase intent begin moving in the right direction. That is where fresh court activity, discharge data, and disciplined follow-up create opportunity.
When Do Mortgage Prospects Qualify?
There is no one-size-fits-all bankruptcy waiting period. Conventional, FHA, VA, USDA, non-QM, portfolio, and private lending programs all have different rules. Individual lender overlays can add another layer. A prospect may meet an agency guideline and still fail a lender’s internal credit, income, or documentation requirements.
That is why smart mortgage acquisition does not treat bankruptcy leads as a single bucket. Segment the data by chapter, filing date, discharge date, dismissal status, geography, and age of record. Then align outreach with the programs your company actually funds.
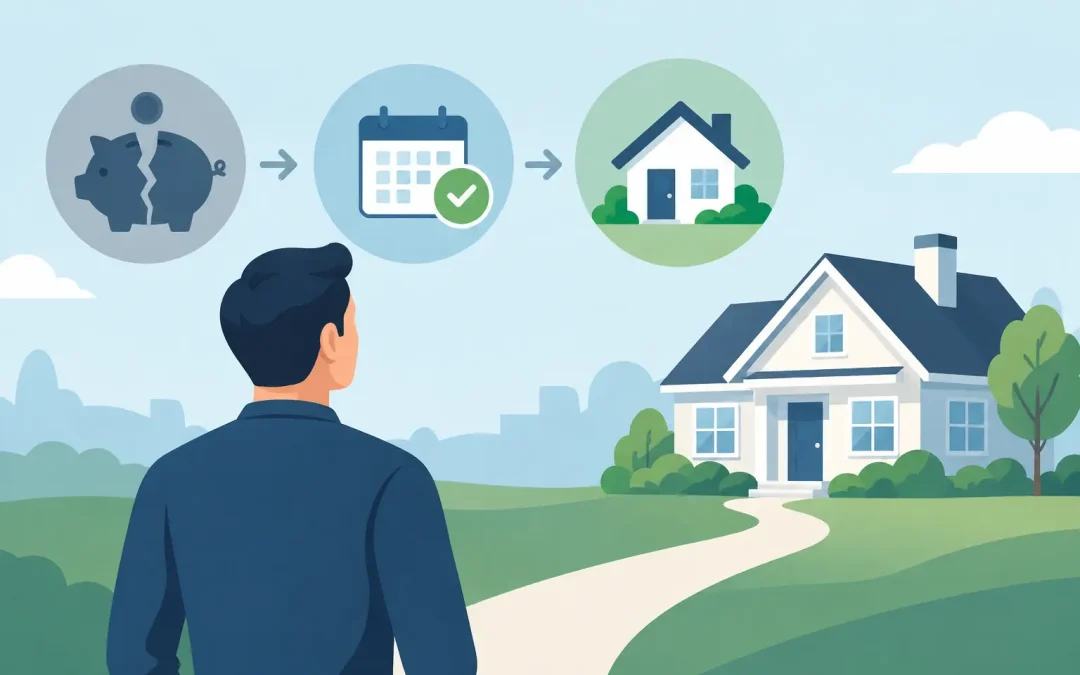
For many borrowers, the mortgage path starts before formal eligibility. A household that has just filed may be years away from a conventional mortgage, but it may be highly responsive to credit-rebuild education, a future-homebuyer plan, or a scheduled check-in sequence. A borrower with a recent discharge may be closer to a viable FHA, VA, or specialized lending conversation than generic credit scores alone would suggest.
The timing is not theoretical. It determines whether your mail piece gets saved, ignored, or turns into an appointment.
The Bankruptcy Event Changes the Qualification Timeline
Chapter 7: A reset, then a rebuild
Chapter 7 generally liquidates eligible unsecured debt and ends with a discharge for qualifying filers. From a mortgage prospecting standpoint, the discharge date is often the key marker. It signals that the borrower’s old debt burden may have been cleared and that the credit-rebuilding phase can begin.
Waiting periods vary by program and borrower circumstances. FHA financing has historically offered a shorter path than conventional financing for many Chapter 7 borrowers, while VA and USDA rules may differ. A lender may also require re-established credit, documented on-time payments, stable employment, adequate cash reserves, and a clean explanation of the event.
Do not market a guaranteed approval based solely on a discharge. Market a review. The strongest message is specific: the prospect may be eligible to discuss available mortgage options, a credit-recovery plan, or a future qualification date. That language drives response without making promises your underwriter cannot support.
Chapter 13: The repayment plan matters
Chapter 13 is different. The borrower repays debts under a court-approved plan, usually over several years. Depending on the loan type, the borrower may be able to pursue a mortgage while still in the repayment plan, but lender approval and trustee permission can be required. Payment history under the plan is critical.
For this audience, Chapter 13 data should never be treated as a simple recent-bankruptcy campaign. A fresh filing is usually an early-stage contact, not an immediate loan application. A seasoned Chapter 13 record with a history of plan payments may deserve a different message. A discharged Chapter 13 prospect may be entering an even stronger mortgage conversation.
The operational takeaway is simple: separate active cases, dismissed cases, and discharged cases. Blending them into one campaign destroys relevance and wastes postage.
Dismissed cases require a closer look
A dismissed bankruptcy does not automatically mean a bad lead. It means the case did not end in a discharge. The prospect may have voluntarily dismissed, missed requirements, or changed financial direction. Their debt picture can be more complicated, and qualification may depend on factors unrelated to the court record.
For mortgage marketers, dismissed records are usually better suited to a softer, compliance-reviewed credit consultation offer than an aggressive mortgage approval message. They can still convert, but they require better screening and a sales team that knows how to work imperfect files.
Qualification Is More Than a Waiting Period
A bankruptcy waiting period is only one gate. Mortgage prospects also need the ability to repay the loan. That means verified income, manageable debt-to-income ratio, acceptable credit profile, assets for closing or down payment where required, and property eligibility once they identify a home.
Credit recovery is where many campaigns either win or lose. A borrower can be technically past the required bankruptcy seasoning period but still have late payments, new collections, unstable income, or insufficient credit depth. On the other hand, a borrower with modest scores may qualify through an FHA, VA, non-QM, or portfolio program when a conventional lender says no.
That is why the best direct-response campaigns sell the next step, not a fantasy. Offer a mortgage readiness review, a no-obligation prequalification conversation, or a personalized timeline. Let the loan officer determine the product fit after collecting the facts.
Use Court Data to Time the Conversation
Freshness is not a feature. It is the whole game.
If you buy a generic credit list that is six months or two years old, you are competing after the consumer has already received piles of offers, repaired their credit elsewhere, or simply moved on. Court-based records give mortgage marketers a clear trigger event. The record tells you where the prospect may be in the financial-reset cycle.
A practical campaign structure often has three tracks. Recent filers receive a long-term recovery message. Seasoned cases receive education around preparing for a future purchase. Recent discharges receive a more direct invitation to review mortgage options and determine whether they are within reach.
The exact cadence depends on your geography, loan products, staffing capacity, and compliance process. A local lender that can work FHA and VA files may prioritize certain discharge windows differently than a broker focused on non-QM borrowers. There is no advantage in mailing every name the same headline when the underlying qualification path is different.
RED-INK delivers court-based bankruptcy records on a manageable weekly schedule, which gives marketers the control to build those segments instead of dumping budget into stale mass data. Weekly delivery also lets you test offers, measure call volume, and improve your follow-up before the next batch arrives.
Build Mail That Produces Calls, Not Complaints
Mortgage outreach to consumers with bankruptcy history must be accurate, respectful, and compliant. Your marketing and legal teams should review applicable federal, state, privacy, fair lending, credit, and solicitation rules before deployment. Do not imply government affiliation, state that a consumer is approved when they are not, or misrepresent loan terms, rates, fees, or eligibility.
Beyond compliance, plain language performs better. Prospects know their financial history. They do not need a letter that talks down to them or makes them feel exposed. They need a credible reason to call.
A strong mailer acknowledges a fresh start without overpromising. It explains that options may be available based on credit, income, loan program, and bankruptcy timing. It gives a direct call to action and makes it easy to respond. If your sales team cannot clearly explain what happens after the call, the campaign is not ready to mail.
Speed matters after response. A prospect who calls after receiving a bankruptcy-related mortgage offer is actively raising their hand. Route that call to someone who can assess the chapter type, dates, income, credit direction, and homebuying goal without forcing the consumer through a generic script.
Measure the Window That Actually Converts
Do not judge a bankruptcy mortgage campaign solely on immediate funded loans. Track response rate, contact rate, completed consultations, credit-review appointments, prequalifications, applications, approvals, and funded volume by record age and bankruptcy status.
Those numbers reveal your real qualification window. You may find that a certain discharge range produces fewer calls but stronger applications. Another segment may generate inexpensive leads that need six to twelve months of nurture before they become financeable. Both can be profitable if you know what you are buying and follow up with discipline.
The mortgage prospect who cannot qualify today may be your best borrower next year. Contact them at the right point in the recovery cycle, give them a believable next step, and keep your data fresh. That is how a bankruptcy record becomes a mortgage opportunity instead of another name wasted on a stale list.