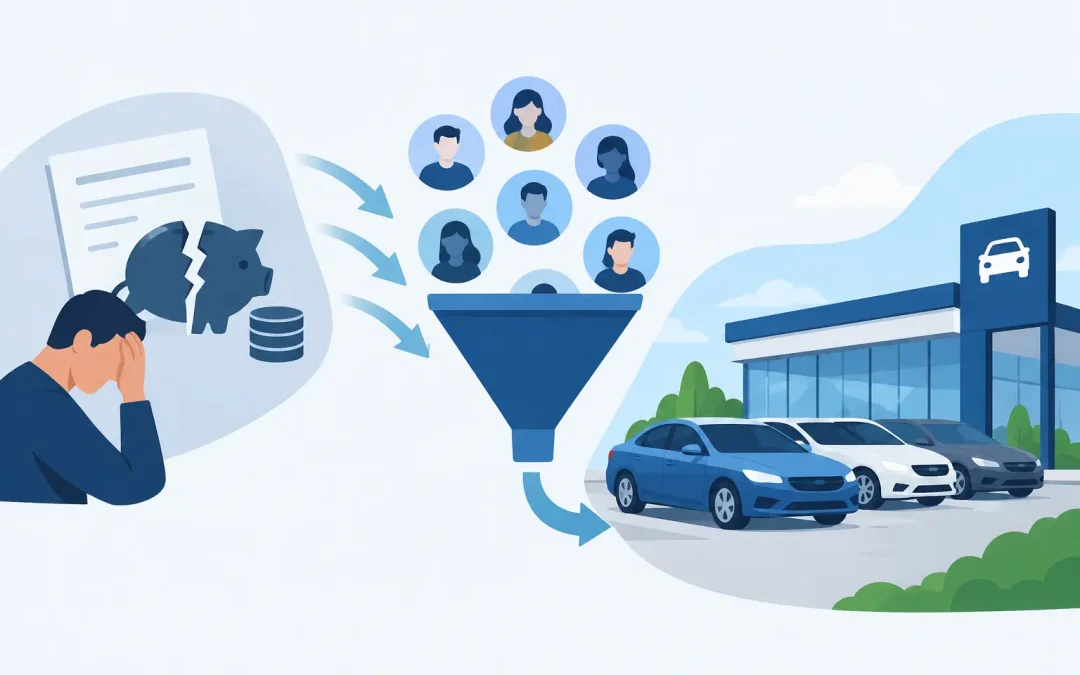
A special finance manager can spend thousands mailing generic credit-challenged households and get little more than bad addresses, duplicate names, and tire-kickers. Ask where do bankruptcy leads come from, and the real answer is not a mystery database or an old credit file. The leads that matter originate with bankruptcy court activity, then get processed, filtered, targeted, and delivered while the consumer’s situation is still relevant.
That timing is the difference between a prospect list and a LEADS MACHINE. A bankruptcy filing, dismissal, discharge, or aging event can signal a major financial reset. For auto dealers, lenders, mortgage professionals, and direct-response marketers, that reset creates an opportunity to put a realistic offer in front of a buyer who may be ready to act.
Where Do Bankruptcy Leads Come From? Start With Court Activity
Bankruptcy cases are filed through the federal bankruptcy court system. Those filings create public records containing case information that can be collected and organized for lawful business use. A quality bankruptcy-data provider monitors that court activity, pulls applicable records, standardizes the data, and turns it into a usable prospect file.
The raw record alone is not a campaign. Court data can include names, addresses, case numbers, filing dates, chapter information, attorney details, and case status. Before it has value to a local dealership or mortgage marketer, it must be matched to the right geography, screened for completeness, formatted for mailing or CRM use, and delivered quickly enough to support a relevant offer.
That is why a list scraped once and sold repeatedly is a weak buy. It may technically contain bankruptcy records, but it does not reflect current court activity or the timing your sales operation needs. Freshness is not a nice extra in this market. It is the product.
The Four Bankruptcy Events Marketers Track
Not every bankruptcy record represents the same sales opportunity. Strong campaigns separate consumers by the event that triggered the record and build the message around that point in the buyer’s timeline.
New bankruptcy filings
A new filing identifies consumers at the beginning of the bankruptcy process. These records can be useful for businesses that have a compliant, practical offer for people dealing with immediate transportation or financial changes. However, this is not always the right segment for every advertiser. Lending eligibility, court restrictions, and a consumer’s ability to transact can vary substantially at this stage.
For many special finance dealerships, filings are a volume source that requires precise underwriting, an appropriate campaign message, and a sales team that understands the situation. A filing is a financial event, not a blanket approval signal.
Bankruptcy discharges
A discharge is often the most actionable event for high-ticket direct marketing. It indicates that the bankruptcy process has reached a pivotal point, and the consumer may be focused on rebuilding credit, replacing a vehicle, refinancing, or reestablishing financial stability.
For an auto dealer, the message is straightforward: a recent discharge may mean the buyer has a cleaner path to financing than they did before. For mortgage marketers, the timeline is more nuanced because loan-program rules, waiting periods, credit profile, occupancy, and other underwriting factors all matter. The record creates a prospecting opportunity. It does not replace qualification.
Dismissed cases
A dismissed case can also be useful depending on the offer and the marketer’s risk rules. Dismissal means the case did not proceed to completion, but the underlying financial pressure may still be very real. These prospects may need transportation, debt solutions, or other services, yet they should not be treated as interchangeable with discharged consumers.
Seasoned bankruptcy records
Seasoned data refers to records that have aged beyond the newest filing or discharge window. It can be less expensive and may work well for broader reactivation efforts, long-cycle campaigns, or markets where fresh weekly volume is limited. The trade-off is obvious: as records age, the original financial trigger loses urgency and the chance that competitors have already contacted the consumer rises.
A smart buyer uses seasoned records deliberately. They do not buy aged data because it is cheap, then expect it to perform like fresh court activity.
How Court Records Become a Marketable Lead File
The source is public court activity. The value comes from the work done after collection. Reliable providers take court-based records through a process that makes them usable for direct response rather than merely interesting to look at.
First, the data is collected on a regular schedule. Weekly delivery is especially valuable because it gives a local sales operation manageable batches rather than a massive list dumped on the team once a quarter. Your BDC, salespeople, mail house, or call center can work the records before they become stale.
Next comes normalization. Names and addresses need to be standardized so the file can be matched, mailed, sorted, deduplicated, and loaded without turning into an operations problem. Geographic filtering matters here. A store in Dallas does not need a national file full of records outside its lending footprint. It needs local records that fit its market, branch territory, or mail radius.
Then comes segmentation. The best list is rarely “everyone who filed bankruptcy.” A dealer may want recent Chapter 7 discharges in specific counties. A mortgage professional may need a separate audience based on discharge age and program eligibility. A lender may exclude certain case types, dates, or locations. The narrower the usable buying criteria, the less money gets wasted on mail and follow-up.
Finally, the records must be delivered in a format built for execution. A clean spreadsheet or data feed with the fields your mail house and CRM require lets the campaign move immediately. If your team has to repair the data for three days, your timing advantage is gone.
Why Fresh Data Beats a Bigger List
Generic consumer lists are built to impress buyers with record counts. Court-based lead generation should be built to produce appointments, applications, and funded deals.
A 50,000-name file sounds powerful until you discover it contains aged records, broad geography, old addresses, and consumers who have already received the same postcard from five competitors. A smaller weekly delivery of current, targeted records can be more profitable because your marketing dollars are concentrated where the trigger event is still recent.
Freshness also improves campaign management. You can test one offer, track response, adjust the creative, and improve the next week’s drop. With a giant stale file, feedback arrives too late and the campaign becomes harder to diagnose. Was the problem the offer, the list, the mail piece, the market, or simply the age of the data? Weekly records make the answer clearer.
RED-INK is built around this operating model: local bankruptcy court records delivered on a recurring schedule for marketers who need to work leads now, not inventory data for later.
Match the Lead Type to the Offer
The record should shape the outreach. A recent discharge prospect may respond to a direct-mail piece focused on rebuilding, a realistic vehicle payment, and a clear path to get pre-qualified. A broad “bad credit accepted” message may get attention, but it can also create unqualified volume and frustrate the sales desk.
For mortgage campaigns, avoid promises that outrun underwriting. The prospect may be eligible for a future conversation, a credit-rebuild plan, or a program-specific review, but eligibility depends on far more than a bankruptcy date. Strong copy gets the consumer to take the next credible step instead of implying an approval you cannot deliver.
The same rule applies to frequency. Contact too early or too aggressively, and your message can feel disconnected from the consumer’s reality. Wait too long, and another dealer, lender, or broker gets there first. There is no single perfect window for every product, market, and case type. The advantage is having current data so you can choose the window rather than being forced to work whatever an old list gives you.
Data Quality Is More Than a Clean Address
A usable bankruptcy lead file needs accurate identity and address information, clear event dates, geographic relevance, and enough case detail to support segmentation. It should also be current enough to match the campaign’s purpose. These are basic requirements, not premium upgrades.
Marketers also need their own compliance process. Public-record availability does not eliminate obligations under applicable federal, state, and local laws, postal rules, consumer-protection standards, licensing requirements, or internal suppression policies. Use truthful offers, maintain opt-out handling where required, and make sure your creative and follow-up practices match the rules governing your business. Court data is a prospecting signal, not permission to make reckless claims.
The practical question is not whether bankruptcy leads exist. They do. The question is whether the supplier gives you timely, local, properly organized court activity that your team can turn into action before it loses value. Buy the event, target the market, work the records fast, and let your results determine the next week’s campaign.